490,000+ drivers found their agreements with us
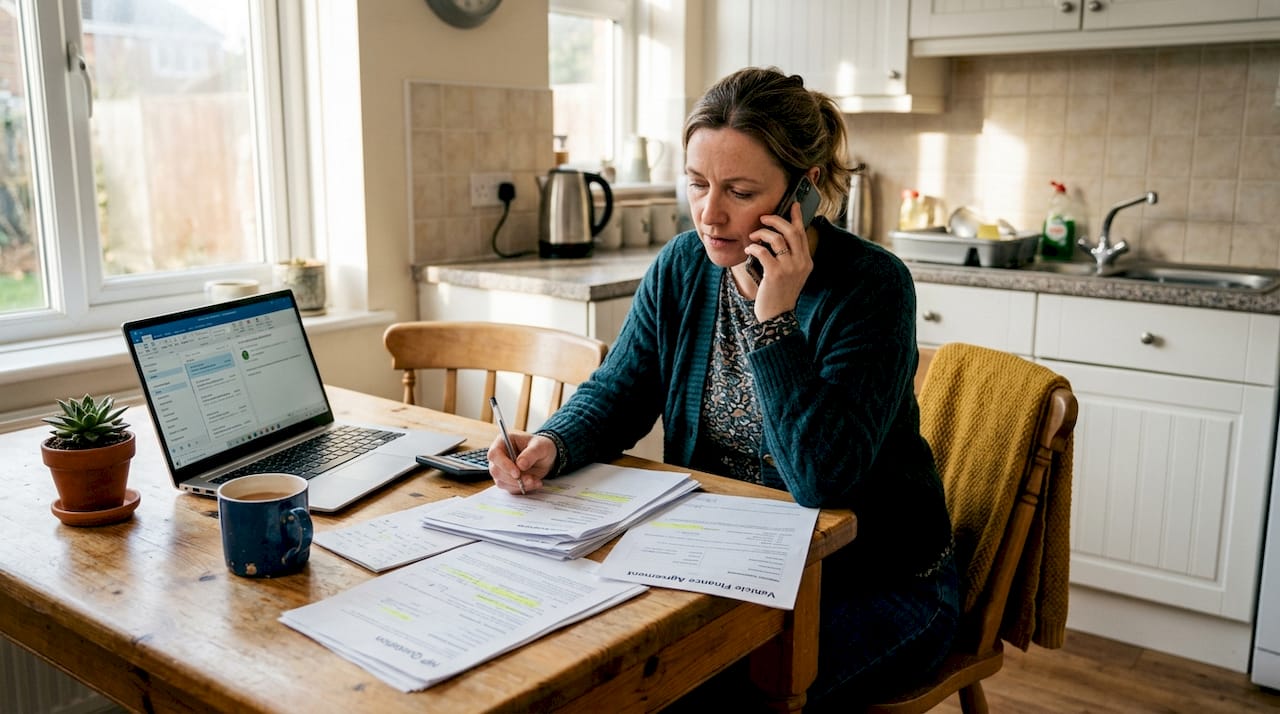
Navigating a mis-sold car finance claim can feel overwhelming, especially when you’re unsure whether to tackle it yourself or seek professional help. Many UK car owners find themselves stuck between wanting full compensation and needing expert guidance through complex lender negotiations. Car claim services promise to simplify the process with no-win no-fee arrangements and specialist knowledge, but understanding their true advantages helps you make an informed choice that suits your situation and maximises your potential redress.
| Point | Details |
|---|---|
| Expert handling benefits | Professional car claim services provide specialist guidance that can simplify complex lender negotiations and paperwork. |
| DIY claims risks | Tackling a claim without help can retain full redress but demands significant effort and risks missing hidden charges. |
| Fees up to thirty percent | Some car claim firms may charge a substantial share of the compensation, potentially as much as thirty per cent. |
| Negotiation with lenders | Experienced claim handlers negotiate with lenders and the Financial Ombudsman Service to secure more favourable outcomes. |
Selecting the right car claim service requires careful evaluation of several critical factors that directly impact your claim outcome and experience. Understanding these criteria helps you distinguish between genuine specialists and companies that may not deliver the value you need.
No-win no-fee policies stand out as the most important feature to verify. This arrangement means you pay nothing upfront and only incur fees if your claim succeeds, removing financial risk from the equation. However, you must read the terms carefully because some providers include hidden charges for administrative tasks or disbursements that apply regardless of outcome.
Expert review capabilities separate quality services from mediocre ones. The best providers employ specialists who can spot discretionary commission arrangements, undisclosed broker fees, and other mis-selling indicators that you might miss. They understand how lenders structure finance agreements and know exactly where to look for evidence of unfair practices.
Negotiation skills with lenders and the Financial Ombudsman Service matter enormously. Experienced claim handlers know how to present evidence persuasively, counter lender objections, and navigate the FOS complaint process efficiently. Their track record in securing favourable settlements often justifies their fees, particularly in complex cases involving multiple finance products or disputed documentation.
Reputation and success rates provide concrete evidence of a provider’s effectiveness. Look for:
Transparency around fee structures should be non-negotiable. Reputable services clearly explain their percentage charges, when fees become payable, and what happens if your claim fails. They provide written agreements detailing all terms before you commit, ensuring you understand exactly what portion of any compensation you’ll keep.
Professional car claim services deliver several compelling advantages that can transform a stressful, uncertain process into a manageable experience with improved success prospects. These benefits become particularly valuable when dealing with lenders who have sophisticated legal teams and established defences against mis-selling claims.
Specialists manage all complex paperwork and strict deadlines, removing the administrative burden from your shoulders. They handle correspondence with lenders, compile evidence packages, and ensure submissions meet regulatory requirements. This saves you countless hours of research and reduces the risk of procedural errors that could weaken your claim or cause rejection.
No-win no-fee arrangements eliminate upfront costs, making professional help accessible regardless of your current financial situation. You don’t pay legal fees, expert consultation charges, or case management costs unless your claim succeeds. This model aligns the service provider’s interests with yours because they only profit when you receive compensation.
Car claim services excel in evidence gathering and lender negotiation, applying their deep knowledge of finance regulations and mis-selling patterns. They recognise subtle indicators of unfair practices that non-specialists often overlook, such as commission structures that incentivised brokers to recommend unsuitable products or failures to conduct proper affordability assessments.
Higher success probability results from professional evidence gathering and presentation. Claim handlers know which documents strengthen your case, how to obtain records from reluctant lenders, and how to frame your complaint for maximum impact. Their experience with similar claims means they can anticipate lender defences and prepare counter-arguments in advance.
Key advantages include:
Pro Tip: Request a detailed breakdown of all potential fees before signing any agreement, including what happens if your claim partially succeeds or settles for less than expected.
Potential fee deductions from compensation mean you must weigh cost against benefit carefully. Whilst FOS data shows rising complaints driven by car finance with significant upholds, service fees can reduce your net redress by up to 30%. Calculate whether the increased success likelihood and reduced effort justify this cost in your specific circumstances.
Understanding the trade-offs between handling your claim independently and using professional services helps you make a choice aligned with your priorities, capabilities, and claim complexity. Each approach offers distinct advantages and challenges that affect both your experience and final compensation.
DIY claims keep 100% of any compensation you receive because you pay no service fees or commissions. This approach makes financial sense for straightforward cases where mis-selling is obvious and you feel confident navigating the process. You maintain complete control over timelines, communication, and settlement decisions without relying on third parties.
However, DIY claims require significant time investment and understanding of finance regulations. You must research your rights, identify relevant evidence, draft formal complaints, and potentially argue your case with the Financial Ombudsman Service. DIY claims keep 100% compensation but require significant effort, and mistakes in presentation or missing deadlines can jeopardise otherwise valid claims.
| Factor | DIY claim | Car claim service |
|---|---|---|
| Cost | No fees, keep full compensation | Typically 20-30% of awarded amount |
| Expertise required | Must understand regulations yourself | Specialists handle legal complexities |
| Time commitment | Substantial research and correspondence | Minimal involvement after initial consultation |
| Success likelihood | Variable, depends on your knowledge | Generally higher due to professional handling |
| Stress level | Can be high, especially if lenders dispute | Lower, professionals manage negotiations |
| Control | Complete autonomy over process | Must trust service provider’s judgement |
Car claim services simplify the process dramatically and provide expert guidance, but their fees reduce your net redress. For complex cases involving discretionary commission models or disputed facts, professional help often proves worthwhile because specialists know how to build compelling evidence packages that overcome lender objections.
Risk of incomplete claims runs higher in DIY approaches without specialist knowledge. You might miss critical mis-selling indicators, fail to request key documents, or present your case in ways that don’t resonate with ombudsmen. Industry warnings against using multiple claims management companies simultaneously highlight another risk because conflicting submissions can damage your credibility and confuse the complaint process.
Pro Tip: If you start with DIY and feel overwhelmed, you can switch to professional help, though some services may charge higher fees for cases they didn’t initiate.
Consider your personal capacity and urgency when choosing your approach. If you have limited time, find legal jargon intimidating, or face health issues that make extensive correspondence difficult, professional services deliver clear value. Conversely, if you enjoy research, have relevant experience, and your claim is relatively simple, DIY may be the smarter financial choice.
Certain situations and claim characteristics make professional car claim services particularly valuable, often justifying their fees through improved outcomes and reduced stress. Recognising these scenarios helps you decide when expert help makes practical and financial sense.
Complex cases with hidden commissions or intricate finance structures need expert analysis. If your agreement involves multiple products, refinancing, or broker arrangements you don’t fully understand, specialists can untangle these complications and identify mis-selling that isn’t immediately obvious.
Lack of time or legal confidence favours professional assistance. When your work schedule, family commitments, or personal circumstances prevent dedicated claim management, outsourcing to specialists ensures your claim progresses without overwhelming your daily life.
Previous claim failures suggest professional negotiation could succeed where DIY attempts didn’t. If lenders rejected your initial complaint or the FOS didn’t uphold your case, specialists might identify new evidence or present existing facts more persuasively on appeal.
Preferring a no-win no-fee guarantee for financial risk control makes sense when you cannot afford upfront legal costs or want certainty about expenses. This arrangement protects you from paying for unsuccessful claims whilst still accessing professional expertise.
Needing help with proof gathering and lender correspondence becomes critical when lenders refuse document requests or provide incomplete records. FCA and MoneyHelper recommend DIY for maximum payout but recognise evidence-gathering strength of professionals who know exactly what to request and how to compel disclosure.
Facing aggressive lender defences or legal counter-arguments requires matching their sophistication. When lenders deploy legal teams to contest claims, having professional representation levels the playing field and prevents you from being outmanoeuvred by superior resources.
Managing multiple finance agreements simultaneously becomes unwieldy without professional coordination. If you have several potentially mis-sold products, specialists can handle all claims efficiently whilst identifying patterns that strengthen each individual case.
If you’re ready to pursue compensation for mis-sold car finance without the stress of managing every detail yourself, professional claim services offer a practical solution. Their no-win no-fee structure means you risk nothing upfront whilst gaining access to specialists who understand exactly how to build compelling cases and negotiate with lenders.

Taking the first step costs nothing and provides clarity about your claim’s strength and potential value. A free initial assessment reviews your finance agreement, identifies possible mis-selling, and explains your options without obligation. Visit Make a PCP claim to connect with experienced professionals who can evaluate your situation and guide you towards the compensation you deserve, handling all the complex work so you can focus on what matters most.
Most claims management companies charge between 20% and 30% of any compensation awarded, though some may charge less for straightforward cases. Always request a written fee agreement before proceeding, and verify whether VAT applies to the quoted percentage, as this affects your final payout.
You can engage professional services at any stage, though some providers may charge higher fees for cases they didn’t initiate because they must review existing correspondence and potentially correct earlier missteps. If your DIY claim stalls or faces rejection, professional help can often revive it with fresh evidence or improved presentation.
Timelines vary significantly based on claim complexity and lender responsiveness, but most cases resolve within three to nine months. Lenders have eight weeks to respond to initial complaints, after which you can escalate to the Financial Ombudsman Service, which typically takes an additional three to six months to investigate and decide.
No legitimate service can guarantee compensation because outcomes depend on your specific circumstances and evidence of mis-selling. Reputable providers offer no-win no-fee arrangements, meaning you only pay if they secure compensation, but this differs from guaranteeing success. Be wary of any company promising definite results without reviewing your case details.
Essential documents include your original finance agreement, payment records, and any correspondence with the lender or broker. Professional services can help obtain missing documents through formal requests, but having your initial paperwork ready speeds up the assessment process and helps specialists identify mis-selling indicators more quickly.