490,000+ drivers found their agreements with us
TL;DR:
- You can quickly identify your car finance lender using free online tools and contact them directly with your account details.
- If unresolved, escalate complaints at no cost through the Financial Ombudsman Service, bypassing claims management companies.
The quickest way to query your car finance provider is to locate who holds your agreement, then contact them directly with your account number and vehicle registration. Makeapcpclaim’s free finder does the first part in under 60 seconds — enter your basic details and it surfaces your lender name, agreement type, and reference without any paperwork hunting.
Here is what to do right now:
You do not need a claims management company (CMC) to do any of this. The FCA confirms that customers can contact lenders themselves and escalate to the FOS at no cost.
Pro Tip: Before you pick up the phone, write down exactly what you want to resolve — a settlement figure, a mis-selling concern, or an incorrect charge. A clear question gets a faster, more useful answer.
Knowing where to look saves hours. Work through these sources in order, starting with the fastest.
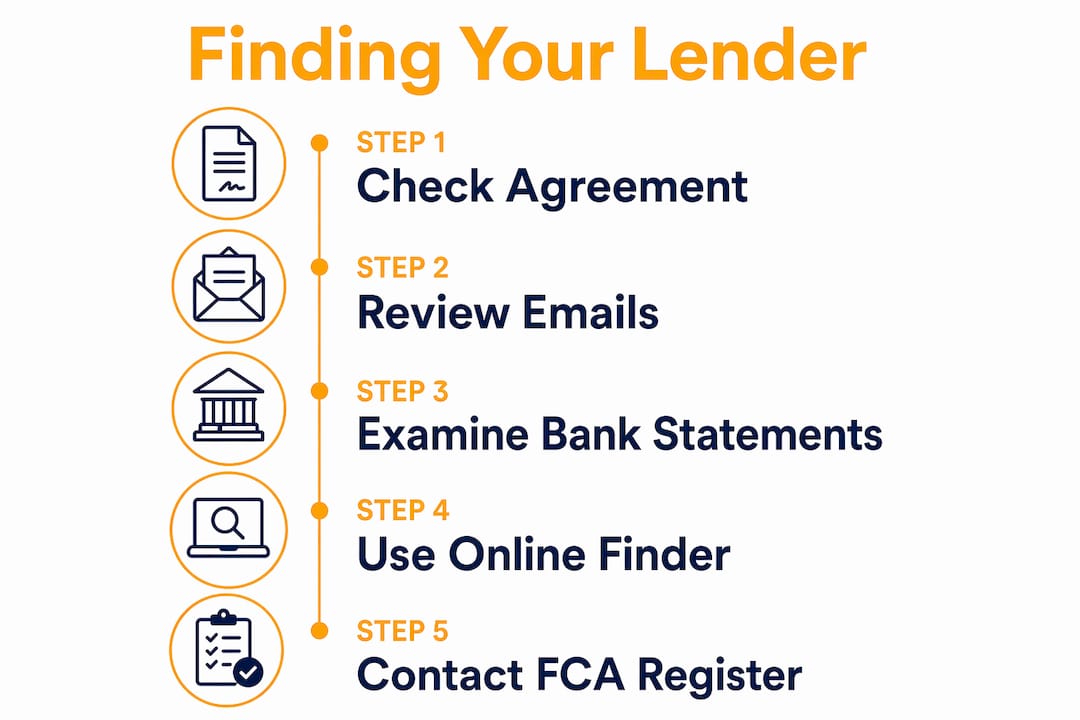
| Source | What it typically shows | Best used when |
|---|---|---|
| Finance agreement document | Lender name, account number, agreement type | You have original paperwork |
| Welcome letter or statement | Servicer name, contact details, account reference | Paperwork is partial |
| Bank statement direct debits | Payee name (often the lender or servicer) | No paperwork at all |
| Dealer correspondence | Finance company name, broker details | You remember the dealer |
| Credit report (Equifax, Experian, TransUnion) | Lender name, account type, opening date | All other sources fail |
| Equifax Car Finance Checker | PCP/HP agreements back to 2007, lender reference | Checking for older or forgotten agreements |
| FCA lender list | Trading name, complaint contact, verification | Confirming a lender is genuine |
If you have none of the above to hand, check your email inbox and bank statements first — dealer confirmation emails and direct debit entries often name the finance company directly.
The FCA publishes a searchable lender list that includes trading names, contact details, and complaint forms. Use it to verify any firm before you share personal information.
Pro Tip: If you only have your vehicle registration, a credit report or the Equifax Car Finance Checker can still surface the agreement reference and lender name — you do not need the original contract to get started.
Not always — and confusing the two wastes time. The lender is the company that owns your loan and is named on your credit agreement. The servicer is the entity that collects your monthly payments, handles day-to-day account queries, and sends your statements. Sometimes they are the same firm; often they are not.
Know the rule before you call: your monthly statement names whoever services your account and includes their contact details and your account reference. That is your first port of call for payment queries, settlement figures, and general account questions. For contractual disputes or formal complaints, you need the lender — the firm named on your original agreement.
Monthly statements typically name the servicer and carry an account reference that speeds up any enquiry. If the statement names a different firm from your agreement, contact the servicer for account matters and the lender for anything contractual.
A well-prepared enquiry gets resolved faster. Lender guidance is clear: include your vehicle registration and finance agreement number in every contact, or staff must search manually, which delays everything.
Collect these before you make contact:
Once you have the documents, note down the specific issue: a settlement figure, an unexplained charge, or a concern about how the finance was sold. Being precise about dates and amounts cuts the back-and-forth considerably.
Pro Tip: Note your preferred callback times and include a direct number in any written contact. Lenders often call back during business hours — if you miss the call, the case sits in a queue again.
Here is a simple preparation sequence:
Once you have your documents ready, choose the right channel for your query type.
Pro Tip: Never call a number found on a random website. Verify it against the FCA register or your original paperwork first. If you are unsure, the FCA helpline can put you through to the lender directly.
Here is a sample written contact you can adapt:
Log every contact: date, time, channel, staff name or reference number, and a summary of what was said. Keep copies of everything you send and receive.
If your query becomes a complaint, the process has a clear structure — and firm deadlines.
The eight-week rule is your key milestone. If the lender has not issued a final response within eight weeks of your complaint, you are entitled to go straight to the Financial Ombudsman Service without waiting further.
The Citizens Advice complaint guidance sets out this stepwise process clearly: contact lender, wait for response, then reply to the lender or escalate to the FOS. When escalating, include a timeline of all contacts, copies of statements, the lender’s final response, and any complaint letters you sent — this shortens FOS handling time.
Pro Tip: Keep your contact details up to date with your lender. If a compensation scheme is active and the lender cannot trace you, they are required to attempt contact by specific deadlines — missing those could exclude you.
A word on CMCs: you can pursue every step of this process yourself. The FCA is explicit that customers do not need a claims management company to contact lenders or escalate to the FOS. Referral to the FOS costs nothing.
Certain patterns in how your finance was arranged are worth scrutinising.
If any of these apply, gather your evidence and submit a complaint to your lender. You do not need to be certain — a complaint triggers the lender’s obligation to investigate.
Pro Tip: The Equifax Car Finance Checker covers PCP and HP agreements going back to 2007. Even if you no longer have the car or any paperwork, it can surface historical agreements you may have forgotten.
The Equifax Car Finance Checker works through the myEquifax app. Sign up for Equifax Basic (free), and the app displays your motor finance history, including lender names and agreement types. Finding an agreement in the app does not confirm entitlement to compensation — it is the starting point for contacting the lender. For any agreement the app surfaces, cross-reference the lender’s details against the FCA register before making contact.
| Tool | What it shows | Limitation |
|---|---|---|
| Equifax Car Finance Checker | PCP/HP agreements from 2007, lender name | Does not confirm compensation entitlement |
| Credit report (Equifax/Experian/TransUnion) | Lender name, account type, payment history | May not show very old or closed accounts |
| FCA lender list | Trading name, complaint contact details | Does not show your personal agreements |
| Makeapcpclaim free finder | Lender name, agreement type, reference | Fastest first check — free, under 60 seconds |
A standard credit report from Equifax, Experian, or TransUnion lists each credit account by lender name, account type (PCP, HP, personal loan), opening date, current balance, and payment history. That is enough to identify who held your finance and when — but the level of detail varies between agencies.
The Equifax Car Finance Checker goes further than a standard credit report for this specific purpose. It is designed to flag PCP and HP agreements, including older ones, and links directly to lender contact details within the app. A standard credit report is broader but may show less detail on the specific agreement type.
Pro Tip: You are entitled to a free statutory credit report from each of the three main credit reference agencies. Order from all three if you are trying to build a complete picture — entries sometimes differ between agencies.
To order your statutory report, go directly to Equifax, Experian, or TransUnion’s websites. Look for the account type column (PCP or HP), the lender name, and the account opening and closing dates. If an entry is incomplete or the lender name is unclear, use the FCA register to match the firm’s trading name.
Makeapcpclaim’s free finder is the fastest first step for most people. Enter your name, date of birth, and address history, and the system searches credit data and internal matching to return your lender name, agreement type, and reference — typically in under 60 seconds.
Privacy note: Makeapcpclaim uses only the information needed to locate your agreement. Personal data is handled in line with FCA-aligned data protection standards. The search does not affect your credit score.
The finder covers most current and historical PCP and HP agreements. It may not surface every closed or very old account in every case — if no match appears, the next step is to order a statutory credit report or use the Equifax Car Finance Checker directly.
Pro Tip: Run the free finder before you do anything else. It takes under 60 seconds and often returns the lender name and agreement reference you need to make contact immediately — no paperwork required.
Once the finder returns your results, you can contact the lender directly using the details on the FCA register, or choose Makeapcpclaim’s optional managed service if you would prefer support preparing your complaint or correspondence.
Contacting your car finance provider directly, with the right documents and a clear question, is the single most effective way to resolve a query or start a compensation claim.
| Point | Details |
|---|---|
| Find your lender first | Use the Makeapcpclaim free finder, your credit report, or the Equifax Car Finance Checker to identify who holds your agreement. |
| Prepare before you contact | Always include your agreement number and vehicle registration — omitting them delays every response. |
| Follow the complaint timeline | Lenders must issue a final response within eight weeks; after that, escalate to the Financial Ombudsman Service for free. |
| You do not need a CMC | The FCA confirms customers can contact lenders and escalate to the FOS themselves at no cost. |
| Makeapcpclaim free finder | Surfaces your lender name, agreement type, and reference in under 60 seconds — free, no paperwork needed. |
Pro Tip: Screenshot or print the results from any online check — the Equifax app, a credit report, or the Makeapcpclaim finder. Having a dated record of what each tool returned is useful evidence if you later escalate to the FOS.
Most people assume querying a car finance provider requires a solicitor or a specialist firm. It rarely does. The complaint process is deliberately accessible: submit in writing, wait up to eight weeks, and escalate to the Financial Ombudsman Service if the response is unsatisfactory. The FOS is free to use and handles the escalation on your behalf.
The part that trips people up is not the complaint itself — it is not knowing who to contact. Once you have the lender’s name and your agreement reference, the rest follows a clear sequence. Keeping a written record of every contact is the one habit that makes the biggest practical difference. A logged timeline of dates, reference numbers, and responses is exactly what the FOS asks for if a case reaches them.
If you have read this far and still are not sure who your lender is, the free finder on Makeapcpclaim is the fastest way to find out. Most people get their lender name, agreement type, and reference within 60 seconds — no paperwork, no credit impact, no cost.

For those who want to go further, Makeapcpclaim offers an optional managed service that covers the full process: identifying your lender, preparing your complaint correspondence, and guiding you through escalation if the lender’s response is unsatisfactory. Fees, where applicable, are disclosed clearly before you commit to anything.
Whether you handle the query yourself or want support with the paperwork, the free check is the right place to start. Run your free car finance check now and have your lender details in under a minute.
The following official sources are the most reliable references for car finance queries and complaints in the UK.
| Source | Best used for | Link |
|---|---|---|
| FCA lender list | Finding lender contact details, complaint forms, and verifying a firm is genuine | FCA car finance lender list |
| Citizens Advice | Step-by-step complaint guidance and scheme deadline information | Citizens Advice car finance claims |
| Equifax Car Finance Checker | Identifying past and current PCP/HP agreements, including older ones | Equifax Car Finance Checker |
| Financial Ombudsman Service | Escalating unresolved complaints after the eight-week lender window | Financial Ombudsman Service |
| Makeapcpclaim free finder | Fastest first check — lender name and agreement reference in under 60 seconds | makeapcpclaim.co.uk |
This article is general information, not legal or financial advice. Confirm current rules and timescales with the FCA, Citizens Advice, or a qualified professional for your specific situation.