490,000+ drivers found their agreements with us
Yes, many car finance claims are genuine, and UK consumers who bought a car on PCP or HP before November 2024 may be owed compensation. The claim’s legitimacy depends on your specific agreement, not on a general assumption that everyone qualifies. Start with the trusted, free routes, the FCA, MoneyHelper and your lender directly, and use Makeapcpclaim’s free check, which finds your car finance agreements in under 60 seconds with no paperwork needed to get started.
TL;DR:
- Claims generally relate to agreements made between 2007 and November 2024 involving discretionary dealer commissions that may have led to higher interest rates without disclosure.
- Eligibility depends on providing key documents such as the finance agreement, correspondence, and proof of interest rate differences, with older or settled deals unlikely to qualify.
- To verify the legitimacy of a claims firm, check FCA registration, ask for proof of authority, and avoid firms pressuring immediate signing or offering guaranteed payouts.
- Consumers can file complaints directly with lenders using FCA templates, and should escalate to the Financial Ombudsman if responses are unsatisfactory or delayed.
- The ongoing legal challenge to the FCA scheme has paused some payouts but does not prevent filing claims; a free check service can identify potential agreements within 60 seconds.
Between 2007 and January 2021, many lenders let car dealers set their own interest rates on finance deals, then paid the dealer more commission if they charged you a higher rate. That’s a discretionary commission arrangement, or DCA. It gave the person selling you the car a direct financial incentive to make your borrowing more expensive, often without telling you.
The Financial Conduct Authority built a redress scheme around this problem after concluding that widespread failures to disclose commission left borrowers paying more than they should have. Caselaw, including a landmark judgment, has since tested exactly when non-disclosure crosses the line into unlawful conduct, and the answer depends on facts like how much commission changed hands and whether the dealer had a right of first refusal on your finance.
What this looks like in practice:
MoneyHelper reports that people who qualify under the proposed scheme could see average payouts of around £800 to £830 per agreement, though the actual figure swings a lot depending on the loan size and how much extra commission was paid.
Eligibility generally hinges on when you took out the agreement and what type it was. Most claims relate to PCP and HP deals arranged between 2007 and 1 November 2024, when the relevant commission practices were common across the industry.
Before you start gathering paperwork, it helps to know what actually strengthens a claim:
Not every agreement qualifies. Cash purchases obviously fall outside scope, as do some balloon or lease-only arrangements with different commission structures. Agreements taken out after November 2024 sit outside the current redress window entirely, and some older deals may already have been settled through a previous complaint. If you’re unsure which category your finance falls into, that’s precisely the gap a free check service is built to close, since it can identify your agreements without you digging out old files first.
Not every company advertising “free car finance checks” is above board, and the SRA has warned about firms acting without proper client consent or submitting weak, poorly evidenced claims. Verifying a firm takes minutes and saves you from a messy exit later.
Red flags include cold calls that pressure you to sign immediately, adverts claiming a “guaranteed payout,” and firms that dodge questions about who actually receives your compensation.
Pro Tip: Genuine dealers and lenders are entitled to ask for a letter of authority before discussing your case with a third party. If a firm can’t produce one, that’s worth questioning immediately.
You don’t need a claims firm to make a complaint, and doing it yourself costs nothing.
Keep copies of everything you send and receive. If a lender asks for further information, respond promptly with dated documents rather than a vague follow-up call, as this keeps a clear paper trail if your case eventually goes to the ombudsman.
Regulators have flagged a real risk here: consumers can lose roughly 30% or more of their compensation in fees when they use a claims management company, according to FCA guidance. On an £800 average payout, that’s potentially £240 or more gone before it reaches your bank account, for work you could often do yourself for free.
Paid representation can make sense in a genuinely complex case, where evidence is scattered across multiple lenders or the legal argument is unusually technical. Before signing with any firm, ask:
Avoid firms that won’t put their fee structure in writing, or that lock you into a rolling contract with no clear exit route.
The redress scheme has faced a legal challenge that’s currently working through the courts, and this has suspended some lender obligations while the case is resolved. That doesn’t mean claims have stopped, it means the timeline for actual payouts has slowed.
Here’s what that means practically:
You don’t need your finance paperwork, your car registration, or your lender’s name to get started. Makeapcpclaim’s free check runs in under 60 seconds and identifies which car finance agreements you may have held since 2007, based on a handful of basic details you provide.
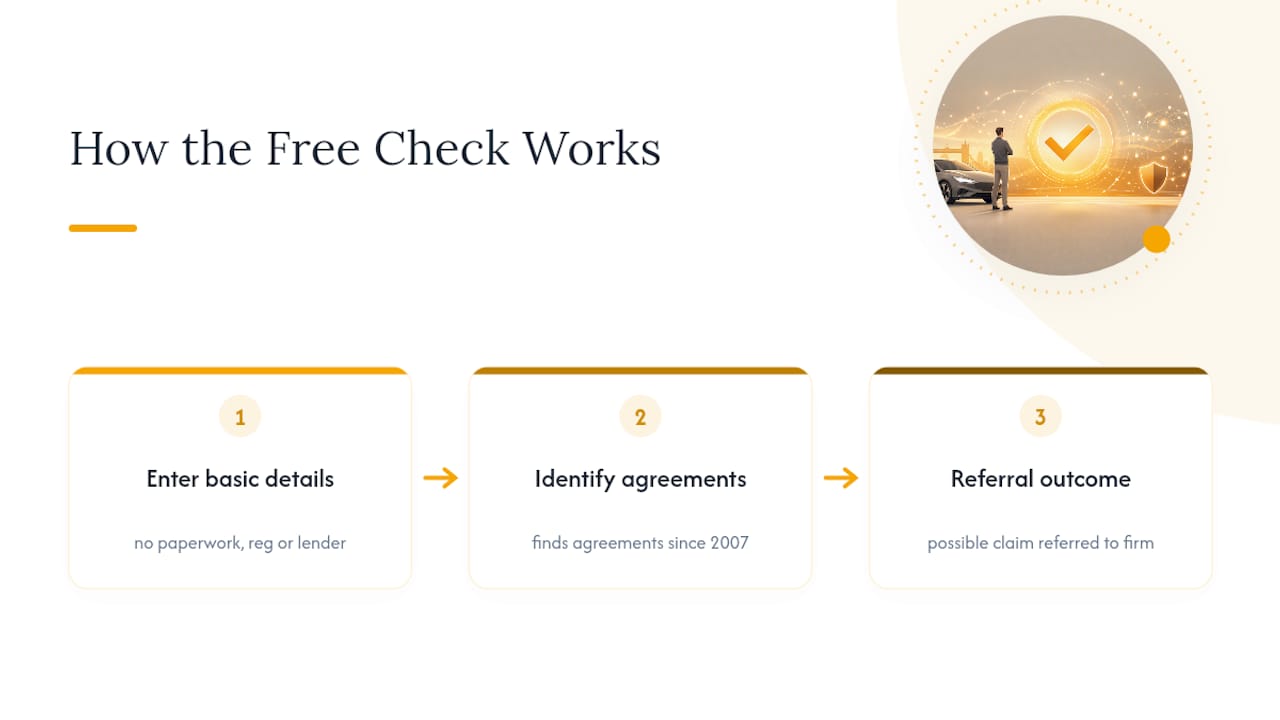
If the check identifies a potentially eligible agreement, your case may be referred to an affiliated law firm to handle the claim on your behalf. You do not pay the referral service directly; any fees are paid by the law firm if the referral proceeds.
That’s not cynicism, it’s just what the numbers say. Most car finance claims are genuine, but the industry around them has attracted some poor actors, and the SRA’s own warnings back that up. Verify before you sign anything, and treat “free” options as your first port of call, not your last resort.
— Jake
Before you spend hours hunting through old paperwork or ringing round former dealers, it’s worth trying the simple route first. Makeapcpclaim’s free check finds your car finance agreements in under 60 seconds, with no car registration and no lender documents required to begin.

If the check turns up an agreement that looks eligible, it may be referred to a partner law firm who handles the claim from there, including gathering the detailed evidence and dealing directly with your lender. You are not charged by the referral service; any referral fee is paid by the law firm. It’s a genuinely lower-effort way to find out where you stand, without committing to anything or paying anyone upfront. Start your free check now and see what it finds.
Bookmark these before you go further, they’re free, accurate, and updated as the situation changes.