490,000+ drivers found their agreements with us
TL;DR:
- Many UK car owners were unknowingly mis-sold PPI in their finance agreements, often unaware of potential claims.
- Using quick, free services can reveal hidden charges, enabling rightful claims that may recover significant money.
Most UK car owners who financed a vehicle in the last two decades gave little thought to payment protection insurance at the time of signing. It was just another line in a thick contract, possibly explained in a sentence or two by a salesperson keen to close the deal. Yet why PPI matters goes far beyond a forgotten paperwork detail. For many drivers over 30, those old agreements may contain mis-sold PPI charges worth hundreds or even thousands of pounds. Understanding the importance of PPI is the first step toward knowing whether you have a legitimate claim sitting untouched.
| Point | Details |
|---|---|
| PPI was widely mis-sold | Millions of UK car finance agreements included PPI without proper explanation or genuine consumer consent. |
| Reclaiming is still possible | Many car owners remain unaware they can still identify and pursue PPI claims from past agreements. |
| Free checks are available | Makeapcpclaim finds your car finance agreements for free in under 60 seconds, removing the biggest barrier to checking. |
| Myths hold people back | Common misconceptions about PPI being unavoidable or claims being too complex stop many from acting. |
| Knowledge protects finances | Understanding your PPI status helps you avoid unnecessary charges and make better financial decisions going forward. |
Payment Protection Insurance is a product designed to cover your loan repayments if you were unable to work due to illness, redundancy, or an accident. In theory, it sounds sensible. In practice, it became one of the most widespread mis-selling scandals in UK financial history.
When you took out a car finance agreement, PPI was frequently bundled in without any clear explanation of what it actually covered. Some lenders added it automatically. Others had dealership staff present it as a requirement rather than an optional add-on. The result was that mis-selling claims remain one of the largest consumer protection cases this country has ever seen.
Here is what typically happened in a car finance context:
This pattern repeated itself across millions of agreements throughout the 1990s and 2000s. Many of those agreements are still retrievable today, which is exactly why the importance of PPI checking has not faded with time.
Understanding why is PPI critical comes down to money. Real, recoverable money that many people have simply left uncollected.
When PPI was added to a car finance agreement, it did not sit as a flat, one-off fee. It was typically calculated as a percentage of the loan and then financed over the same term as the vehicle. So if your car loan was £12,000 over four years and PPI added £1,500 to that figure, you were paying interest on that £1,500 for the full duration. The total cost to you could reach well over £2,000 by the time the agreement ended.
Here is why many car owners still have grounds to explore a claim:
Pro Tip: Do not assume the PPI deadline has passed. While the August 2019 complaints deadline applied to most bank PPI, car finance agreements with undisclosed commission arrangements have separate legal routes, and consumer protection cases continue to evolve in 2026.
Many consumers wrongly believe PPI is an unavoidable or minor fee, which leads them to overlook the cumulative financial impact and the claim opportunities still open to them. The PPI significance explained here is simple: if the product was added without your informed consent, you have a right to pursue it.
The biggest practical obstacle most people face is finding their original agreement. After five, ten, or fifteen years, paperwork gets lost, lenders change names, and the memory of the finance deal fades. This is where speed and simplicity matter.
Makeapcpclaim locates your car finance agreements for free in under 60 seconds. You do not need to hunt through old files or remember which lender you used. The service does the legwork, giving you the information you need to take the next step.
Once you have your agreement details, here is what to look for:
Pro Tip: Even if your agreement does not use the phrase “PPI” explicitly, look for any optional insurance product tied to the finance. Names varied between lenders, and the same mis-selling issue applies regardless of what it was called.
After identifying PPI in your agreement, the next practical step is to assess whether the circumstances of the sale meet the criteria for a claim. You do not need legal expertise for this initial review. Makeapcpclaim guides you through the process, helping you understand what you found and what it means for your claim potential. Seeking professional help at that stage costs you nothing to explore, and the benefit of acting sooner rather than later is that evidence and records are more accessible.
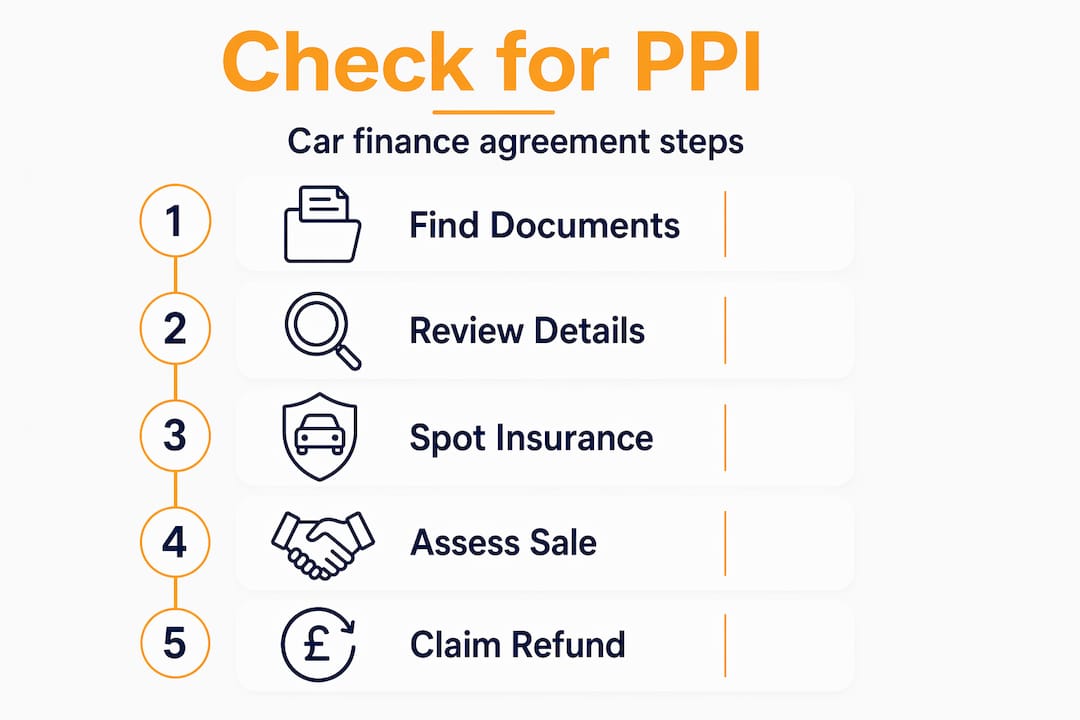
Reviewing protection policies regularly is a sound financial habit for this exact reason. Agreements you signed years ago may contain products you were never meant to pay for.
A significant number of car owners who could pursue a claim never do. Not because their case is weak, but because misunderstandings and myths about PPI deter them before they even start.
| Myth | Reality |
|---|---|
| “The PPI deadline has passed, so it’s too late.” | The 2019 deadline covered bank PPI complaints. Car finance PPI with undisclosed commissions has separate legal routes still active in 2026. |
| “My agreement was too small to matter.” | Even modest monthly PPI charges compound over a multi-year agreement. The total impact is nearly always larger than people expect. |
| “I would have noticed if PPI was in my contract.” | Complex contract language and the way charges were bundled into loan totals made PPI invisible to most consumers at the time of signing. |
| “Claims are too complicated and probably not worth it.” | Free services like Makeapcpclaim simplify the process significantly. Many claims are straightforward once the agreement is retrieved. |
| “PPI must have been fine or the lender wouldn’t have added it.” | The scale of the mis-selling scandal demonstrates the opposite. Lenders added PPI to increase revenue, often without regard for whether the product suited the customer. |
The pattern here is consistent. Consumer awareness remains low not because the claims lack merit, but because the myths feel more believable than the facts. Questioning those assumptions is genuinely worth your time.
Knowing your PPI status delivers value that extends beyond any single claim. The PPI advantages extend to the way you approach every financial product going forward.
When you properly understand what was added to your previous car finance agreement, you become a far more informed borrower the next time you sit across from a finance manager at a dealership. You know to ask which products are optional, to request a clear breakdown of your total repayment, and to take time reading before signing. That knowledge directly reduces the likelihood of paying for products you do not need.
There is also a practical budgeting benefit. Financial empowerment improves when car owners understand all components of their loan agreements. If you discover you have been paying for a product that was incorrectly added, recovering that money can meaningfully affect your current financial position. Whether it covers a car service, reduces an existing debt, or simply adds breathing room to your monthly budget, the impact is real.
Regularly checking your agreements is also a protection against recurring or incorrect fees. Some agreements rolled over or were refinanced, carrying forward PPI charges into new contracts. Catching that pattern early stops unnecessary costs from compounding further.
I’ve spoken with a lot of people over the years who dismissed their old car finance agreements as ancient history. “That was ages ago,” they say, as if the passage of time somehow cancels out money they were wrongly charged. It does not.
What I’ve found is that the people who are most sceptical about checking are often the ones whose agreements reveal the clearest cases of mis-selling. The product was added quickly at a dealership, explained vaguely, and folded into a monthly payment that felt manageable. Nobody questioned it at the time because nobody knew they should.
The low awareness around PPI relevance today is not accidental. Complex paperwork and the normalisation of bundled insurance products made it easy for consumers to overlook what they were actually paying for. Understanding hidden costs in contracts is a skill most people develop only after they have already paid for the lesson.
What I genuinely believe is this: if you financed a car between the early 1990s and 2010s and you have never checked your agreement for PPI, you owe it to yourself to look. It takes less than a minute with the right tool. The upside is potentially substantial. The downside of not checking is that you will never know.
— Jake
If this article has raised questions about your own car finance history, the next step is straightforward. Makeapcpclaim offers a free PPI check that locates your car finance agreements in under 60 seconds. No paperwork required. No lengthy forms to fill out.

The service is built specifically for people in your position: UK car owners who want to know whether PPI was included in their agreement and whether there is a claim to pursue. You do not need to remember your lender’s name or have the original contract to hand. Makeapcpclaim does the searching for you, giving you clear information quickly so you can decide what to do next. Taking 60 seconds to check could be the most financially worthwhile minute you spend this year.
PPI stands for Payment Protection Insurance. In car finance, it was an insurance product added to loans to cover repayments if the borrower could not work. It was frequently mis-sold by being added without clear consumer consent or proper explanation.
Yes, in many cases. While the August 2019 deadline covered certain bank PPI complaints, car finance agreements involving undisclosed commissions have separate legal routes. Makeapcpclaim can help you identify whether your agreement qualifies.
Makeapcpclaim locates your car finance agreements for free in under 60 seconds. Once retrieved, you can review the agreement for any payment protection or loan insurance charges included in your total financed amount.
The amount varies depending on the size of your loan, the PPI premium charged, the interest applied to that premium, and the length of your agreement. Some claimants have recovered several thousand pounds from a single agreement.
Yes. Many car owners assume the amount was too small or too long ago to pursue, but cumulative PPI charges over a multi-year agreement are often significantly larger than people expect. A free check carries no financial risk and takes under a minute.